
The first few weeks of Q2 experienced significant market volatility in response to the proposed “Liberation Day” reciprocal tariffs. Fortunately, the strong stock market reaction (and bond market reaction) sent a signal to policymakers. As a result, on April 9, most of the tariffs were delayed 90 days to July 9. Then, on May 12, the U.S. and China, whose 100%+ tariffs on each other were rapidly choking off trade between the two countries, reached a tariff truce. Reflecting the rapid onset and rapid exit of tariff risks was the fastest high, to bear market, and back to the high cycle in history.
This is shown in Chart 1 (below), where the Feb. ’25 cycle is compared to the other bear market declines of the past fifty years, including the 1981 “Volcker” decline, the Black Monday 1987 crash, the dotcom bubble in 2000, the global financial crisis in 2007-2009 and, most recently, the 2020 Covid decline.
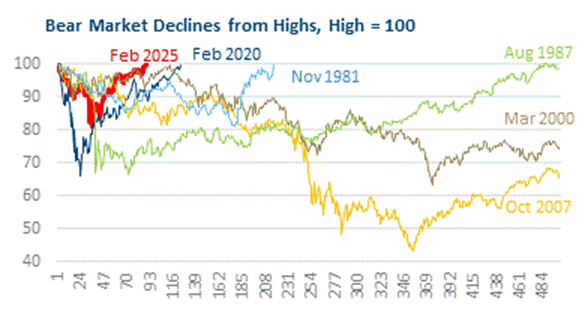
Chart 1
The 2025 decline is even faster than the Feb. ’20 Covid cycle, the prior record holder. Technically speaking, the 2025 decline did not reach a closing bear market, as its maximum drawdown was 19% on April 8, though did meet that level on its intraday low on April 4. Technicalities aside, the speed of the onset, and recovery, was notable. From its Feb. 19 peak, the S&P dropped 19% to its closing low on April 8, with the 12% drop from April 3 to 8 accounting for 60% of the overall decline. The subsequent recovery was equally fast and concentrated, with just two days (April 9’s 10% S&P jump on the 90-day pause and May 12’s 3% rise on the China truce) accounting for 56% of the subsequent recovery to June 27’s new high (conveniently for writers of quarterly reports, just in time for Q2’s end).
The 2025 stock market also had a similar relationship to 2020 with the relative performance of growth and value stocks. Q2 2025 experienced the largest quarterly relative outperformance of growth over value. At 19% versus 3%, the 16% gap easily exceeded the second largest quarter, 14% in Q2’20. There are some similarities between these two quarters. In both cases, a geopolitical risk was bubbling in Q1 (Covid and tariffs) that ultimately proved far more dangerous than expected in the opening weeks of Q2. Subsequently, they recovered to, yet again, show that geopolitical events, while significant in the real world, can quickly pass in the markets. Going a step further, market signals (stocks falling on the recession risk from Covid and tariffs) prompted market reversing policy shifts (Fed and fiscal policy supporting the economy during a shutdown in ’20; 90-day tariff suspensions in ’25). In other words, the strong market reaction to the negative news prompted a recovery, and growth-boosting, policy shift.
While it is certainly a positive that The Bear Market Went Back Into Hibernation as tariff risks receded, the rapid market recovery with a record growth over value surge illustrates that much of the pessimism from the start of the quarter has exited the market. With the market fully recovered from its brief downturn, there is little room for tariff risk if it (or another risk) re-emerges.
See Also
- 6/30/25 Outlook Theme #1: Making Sense of Dollar Changes and International Stock Returns
- 6/30/25 Focal Point: Will the Uncertainty of Trade Policy Be Obscured by a Fed Shadow?
Important Disclosures:
Past performance is not indicative of future results. Different types of investments involve varying degrees of risk. Therefore, there can be no assurance that the future performance of any specific investment or investment strategy (including the investments and/or investment strategies recommended and/or undertaken by Grimes & Company Wealth Management, LLC [“Grimes”]), or any non-investment related content, made reference to directly or indirectly in this blog will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. Due to various factors, including changing market conditions and/or applicable laws, the content in this blog may no longer be reflective of current opinions or positions. Moreover, you should not assume that any discussion or information contained in this blog serves as the receipt of, or as a substitute for, personalized investment advice from Grimes. To the extent that a reader has any questions regarding the applicability of any specific issue discussed above to his/her individual situation, he/she is encouraged to consult with the professional advisor of his/her choosing. No amount of prior experience or success should be construed that a certain level of results or satisfaction will be achieved if Grimes is engaged, or continues to be engaged, to provide investment advisory services. Grimes is not a law firm and does not provide legal advice. Grimes is not a certified public accounting firm. Grimes is affiliated with S&C Tax Advisors, which provides tax preparation and related tax services. Tax services provided by S&C Tax Advisors are separate and distinct from the investment advisory services provided by Grimes and are subject to a separate engagement. Clients are under no obligation to engage S&C Tax Advisors and may obtain tax preparation or other tax services from any provider of their choosing. Information provided by Grimes regarding tax matters in connection with its investment advisory services should not be construed as individualized tax advice or a substitute for services provided by a qualified tax professional. Grimes is not an insurance agent. Grimes Representatives may, however, separately provide insurance products and services through our affiliate, Grimes Wealth Protection Group, LLC. If the client desires, one of Grimes’ representatives, acting in their capacity as a representative of Grimes Wealth Protection Group, LLC or in their separate licensed individual capacities, can be engaged to provide insurance sales/services as described on Grimes’ written disclosure Brochure per the terms and conditions of a separate engagement. Grimes is affiliated with Grimes Trust Services, a corporate trustee that offers trustee services under a separate engagement. Clients are under no obligation to retain Grimes Trust Services for trustee services. Any information provided by Grimes regarding trust matters in connection with its investment advisory services should not constitute trustee services and be considered a substitute for services provided by a qualified professional. Nothing contained herein should be construed as the receipt of, or a substitute for, personalized investment advice from Grimes. A copy of our current written disclosure Brochure discussing our advisory services and fees is available for review upon request or athttps://www.grimesco.com/form-crs-adv/ Please Note: Grimes does not make any representations or warranties as to the accuracy, timeliness, suitability, completeness, or relevance of any information prepared by any unaffiliated third party, whether linked to Grimes’ web site or blog or incorporated herein, and takes no responsibility for any such content. All such information is provided solely for convenience purposes only and all users thereof should be guided accordingly. Please Remember: If you are a Grimes client, please contact Grimes, in writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you would like to impose, add, or to modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please Also Remember to advise us if you have not been receiving account statements (at least quarterly) from the account custodian.