
During a period with several market extremes, one of the most notable developments in the first half of 2025 was the dollar’s decline: The dollar index’s 11% first half decline was its largest since 1973. Part of the large move thus far in 2025 was due to the dollar rising to close out 2024, on the expectation that pending policy moves would be beneficial to the U.S. economy on a relative basis. Instead, the uncertainty of multiple proposed and then suspended tariff regimes, paired with general concern that the relative strength of the U.S. economy relative to other countries could be pressured this year, helped drive this decline.
One of the most notable ways foreign exchange (FX) shows up in investment portfolios is via international stock returns, since stocks denominated in a rising foreign currency will get a value boost as their share prices translate back into dollars. Year to date, this has accounted for 14% of the MSCI EAFE’s 20% return, and, as Chart 1 (below) shows, has boosted returns on a rolling 12-month basis by 9%. This rolling boost is near the top of its +/- 10% range of the past 10 years, which was only significantly exceeded in 2023, a move exacerbated by the prior year’s record dollar drag. As of the end of Q2, the move is getting into extreme territory, though could persist for months, or even quarters.
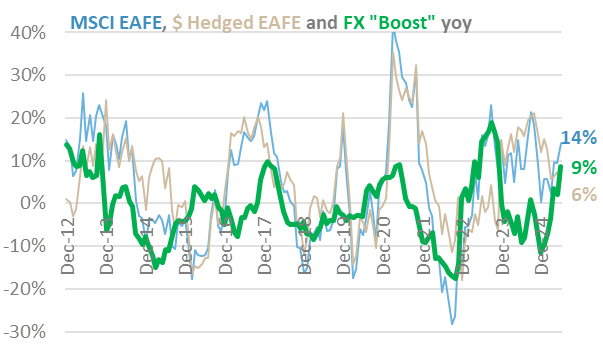
Chart 1
The chart also shows how just six months ago, at the end of 2024, the FX impact was -12%, similarly extreme, but in the opposite direction. Additionally, the impact of currency moves on foreign stocks is not one-sided. While there is an immediate boost to international stock returns from a weaker dollar, it will be counteracted over time by the lower dollar reducing foreign stock profits and U.S.-based companies getting a competitive boost from lower prices. This does not mean international stocks are doomed, but when the dollar eventually stabilizes, the price tailwind will fade quickly while the profit headwind will slowly rise.
While it is moving towards extreme levels, the FX stock boost could continue as long as the dollar is under pressure. While the path for trade policy is hard to gauge, we can look at other drivers of foreign exchange moves. The yield on the 10yr Treasury and the dollar are linked. When yields on U.S. assets, such as the 10yr, rise, that increases demand for U.S. assets. Although the relationship is not perfect, higher yields should coincide with a stronger dollar. But the recent dollar drop has come with steady (not falling) rates. The relationship is most evident when looking at the change in the dollar index and the change in the 10-year Treasury yield.
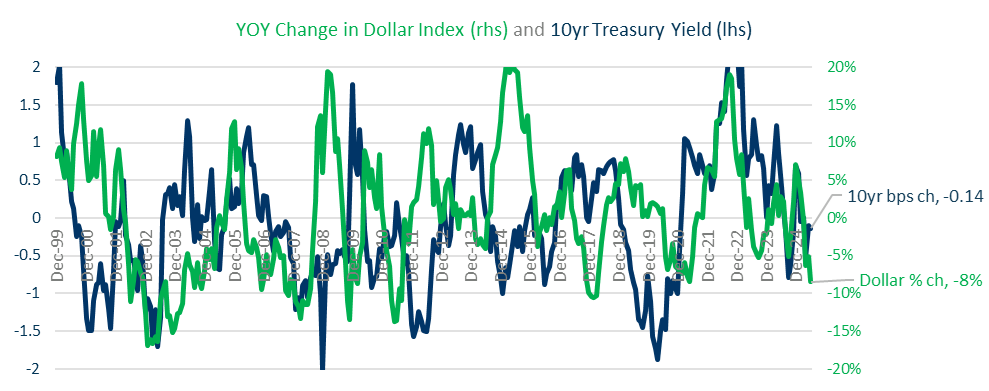
Chart 2
Chart 2 (above) shows that the recent dollar weakness, with an 8% decline, has deviated from the relatively unchanged yield of just 14 basis points on the 10yr Treasury.
The key is to understand how the direction of interest rates and the dollar could factor back into international stock returns. Assuming the markets behave normally, the recent dollar weakness should result in either interest rates falling to catch up, or the dollar recovering to match the still steady U.S. rates. If the first scenario unfolded and rates fell to 4% or below, that could keep the dollar weak and support international stock prices. Conversely, if U.S. rates start to rise towards 5% and the dollar reversed course higher, that could unwind the support for international stocks by removing the foreign exchange tailwind at the same time as those stocks are starting to experience the profit headwind.
The one outlier scenario to keep an eye on is if the dollar continues to fall and interest rates were to rise. This would suggest widespread sales of dollar-based assets. While this is not the most likely outcome, it is one more reason to watch how the current relationship between interest rates and the dollar plays out. This relationship between the dollar, interest rates, and international stock returns is why Making Sense of Dollar Changes and International Stock Returns is important.
See Also
- 6/30/25 Outlook Theme #2: The Bear Market Quickly Goes Back into Hibernation
- 6/30/25 Focal Point: Will the Uncertainty of Trade Policy Be Obscured by a Fed Shadow?
Important Disclosures:
Past performance is not indicative of future results. Different types of investments involve varying degrees of risk. Therefore, there can be no assurance that the future performance of any specific investment or investment strategy (including the investments and/or investment strategies recommended and/or undertaken by Grimes & Company Wealth Management, LLC [“Grimes”]), or any non-investment related content, made reference to directly or indirectly in this blog will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. Due to various factors, including changing market conditions and/or applicable laws, the content in this blog may no longer be reflective of current opinions or positions. Moreover, you should not assume that any discussion or information contained in this blog serves as the receipt of, or as a substitute for, personalized investment advice from Grimes. To the extent that a reader has any questions regarding the applicability of any specific issue discussed above to his/her individual situation, he/she is encouraged to consult with the professional advisor of his/her choosing. No amount of prior experience or success should be construed that a certain level of results or satisfaction will be achieved if Grimes is engaged, or continues to be engaged, to provide investment advisory services. Grimes is not a law firm and does not provide legal advice. Grimes is not a certified public accounting firm. Grimes is affiliated with S&C Tax Advisors, which provides tax preparation and related tax services. Tax services provided by S&C Tax Advisors are separate and distinct from the investment advisory services provided by Grimes and are subject to a separate engagement. Clients are under no obligation to engage S&C Tax Advisors and may obtain tax preparation or other tax services from any provider of their choosing. Information provided by Grimes regarding tax matters in connection with its investment advisory services should not be construed as individualized tax advice or a substitute for services provided by a qualified tax professional. Grimes is not an insurance agent. Grimes Representatives may, however, separately provide insurance products and services through our affiliate, Grimes Wealth Protection Group, LLC. If the client desires, one of Grimes’ representatives, acting in their capacity as a representative of Grimes Wealth Protection Group, LLC or in their separate licensed individual capacities, can be engaged to provide insurance sales/services as described on Grimes’ written disclosure Brochure per the terms and conditions of a separate engagement. Grimes is affiliated with Grimes Trust Services, a corporate trustee that offers trustee services under a separate engagement. Clients are under no obligation to retain Grimes Trust Services for trustee services. Any information provided by Grimes regarding trust matters in connection with its investment advisory services should not constitute trustee services and be considered a substitute for services provided by a qualified professional. Nothing contained herein should be construed as the receipt of, or a substitute for, personalized investment advice from Grimes. A copy of our current written disclosure Brochure discussing our advisory services and fees is available for review upon request or athttps://www.grimesco.com/form-crs-adv/ Please Note: Grimes does not make any representations or warranties as to the accuracy, timeliness, suitability, completeness, or relevance of any information prepared by any unaffiliated third party, whether linked to Grimes’ web site or blog or incorporated herein, and takes no responsibility for any such content. All such information is provided solely for convenience purposes only and all users thereof should be guided accordingly. Please Remember: If you are a Grimes client, please contact Grimes, in writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you would like to impose, add, or to modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please Also Remember to advise us if you have not been receiving account statements (at least quarterly) from the account custodian.